
(Data as of 5 October 2026)
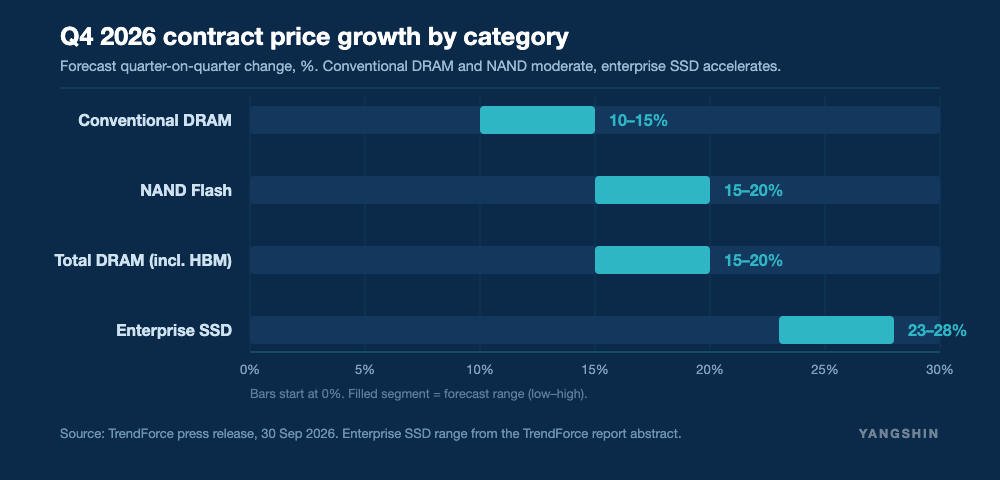
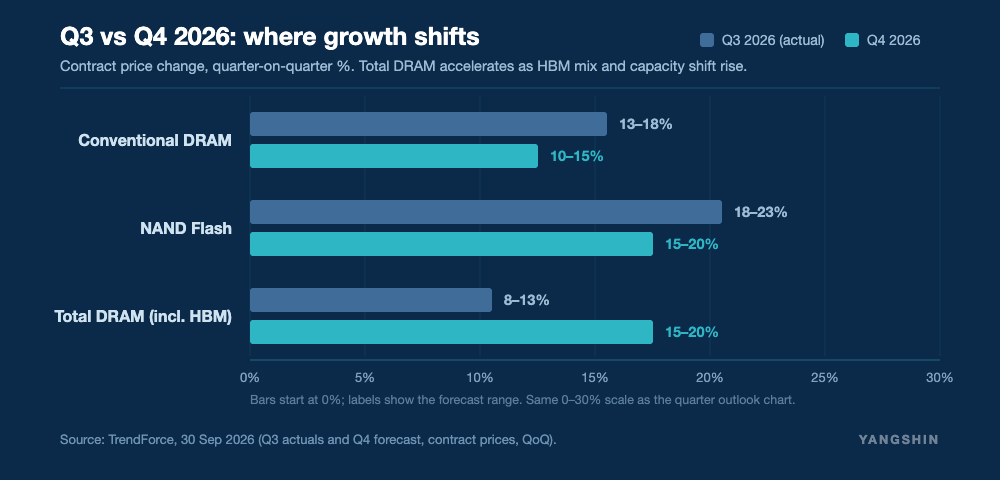
AI servers continue to absorb memory capacity. TrendForce's 30 September forecast puts Q4 2026 conventional DRAM contract prices 10–15% higher quarter on quarter and NAND flash 15–20% higher, with enterprise SSDs up 23–28% — the only category accelerating from the third quarter.
Suppliers point the same way. Micron's fiscal Q4 2026 results, reported on 30 September, showed quarterly revenue of $54.23 billion, up 379% year on year. The company has signed 26 Strategic Customer Agreements covering more than 35% of revenue through 2030, with customer financial commitments rising to $32 billion. Management expects memory and storage supply-demand to be "significantly tighter" in calendar 2027 and 2028 than in 2026.
Pricing for next-generation high-bandwidth memory is climbing in step. Industry reports indicate that Samsung has quoted major customers roughly three times the per-gigabit price of current HBM3E for 2027 HBM4 supply; TrendForce raised its 2027 HBM blended ASP forecast to a 121% year-on-year increase. The quote is not final and remains subject to negotiation.
Passive components are following. Sina Finance reported on 5 October that Murata, Taiyo Yuden and Samsung Electro-Mechanics have each notified customers of price increases, with AI-server high-capacitance MLCC list prices 15–35% higher.
For buyers, commodity DDR5 and high-capacity SSDs are the categories most directly affected by this capacity reallocation, raising the priority of allocation and lead-time management.
YANGSHIN Technology distributes JC Semiconductor, Kangying Semiconductor and Youcun Technology memory and passive component lines.
Memory & Passive Component Distribution
For quotations and lead-time support, please contact the YANGSHIN Technology sales team at sales@yangshin.com

